
South Africa’s food and agricultural supply chains are facing renewed operational pressure after new business survey data showed the country’s private sector contracted at its fastest pace since December 2025.
The latest Purchasing Managers’ Index (PMI), released on 5 October, indicated a sharp decline in new orders across the economy, with businesses reporting ongoing supply-chain disruptions and rising operating costs, particularly fuel-related expenses. These factors contributed to the steepest deterioration in private-sector activity in nine months.
Logistics Costs Remain a Key Risk
For the food industry, logistics remains one of the most critical cost drivers.
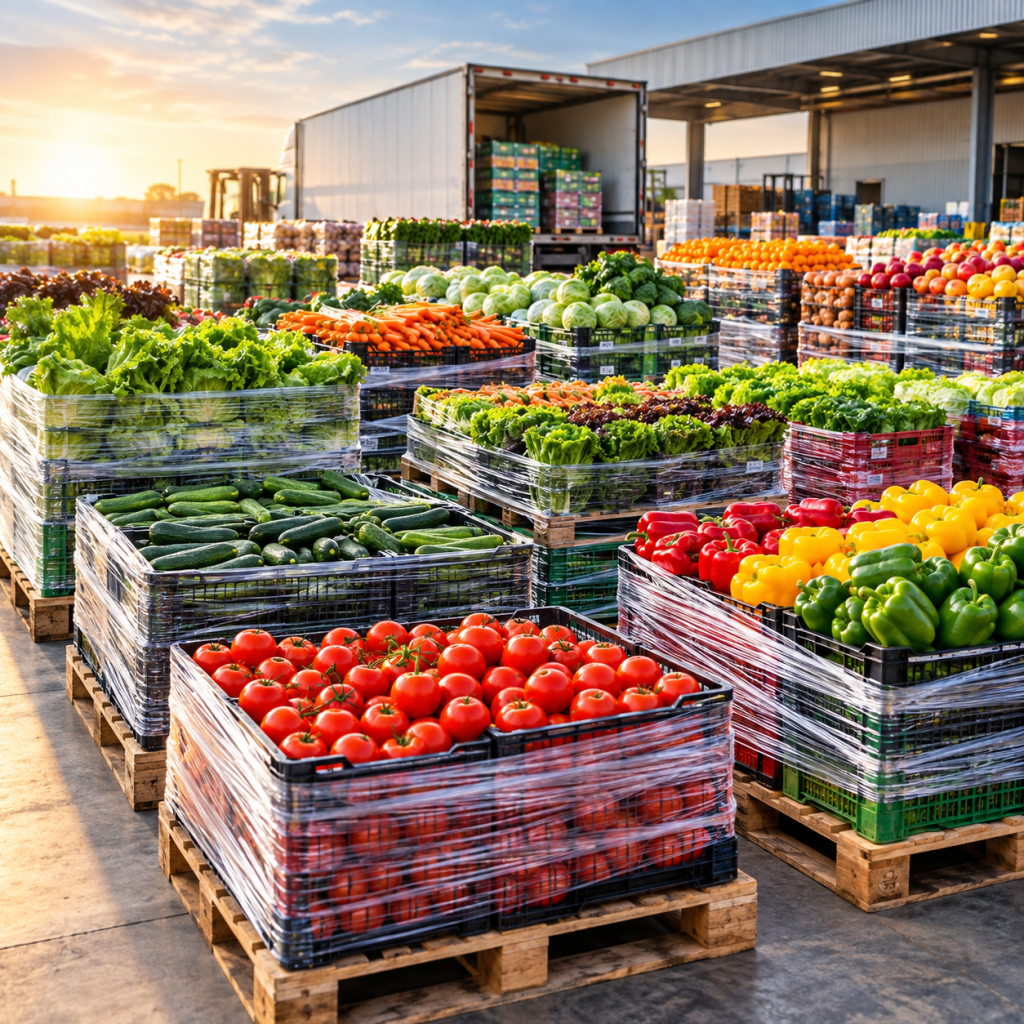
Agricultural producers, food processors, distributors, and retailers rely heavily on road freight networks to move products from farms to processing facilities and retail shelves. Higher transport costs directly affect margins across the value chain, particularly for fresh produce and time-sensitive food products.
Survey respondents cited fuel-related cost pressures as a major factor affecting business conditions during September.
Impact on Food Processing and Distribution
The slowdown comes at a time when South Africa continues to pursue greater agricultural exports, expanded food-processing capacity, and improved regional trade integration through African markets.
A weaker flow of new orders and continued supply-chain challenges could temporarily affect inventory planning, procurement cycles, and distribution efficiency across food-related industries.
However, industry participants continue investing in productivity improvements, technology adoption, and supply-chain resilience to strengthen long-term competitiveness.
What It Signals for Food Systems
While the PMI data reflects short-term pressure rather than a structural decline, it highlights the importance of continued investment in logistics infrastructure, energy reliability, agricultural processing capacity, and transport efficiency.
For South Africa’s food economy, the latest survey reinforces a central reality: competitiveness increasingly depends on resilient supply chains capable of absorbing fuel volatility and operational disruptions.
As producers and processors position for future growth opportunities across Africa and global export markets, supply-chain performance will remain a critical determinant of profitability, food security, and industrial expansion.